Do you have flood insurance? Here's what to consider ahead of potentially historic El Niño winter


SAN FRANCISCO (KGO) -- As our El Niño winter approaches, now is the time to prepare. 7 On Your Side has heard from many of you wondering: "Should I get flood insurance?"
El Niño conditions could arrive well before the heart of winter. And here's why that matters: most flood insurance policies take 30 days to kick in. If you're waiting for the first big storm to decide, you may already be too late.
So, for those who are on the fence, here's what you should know.
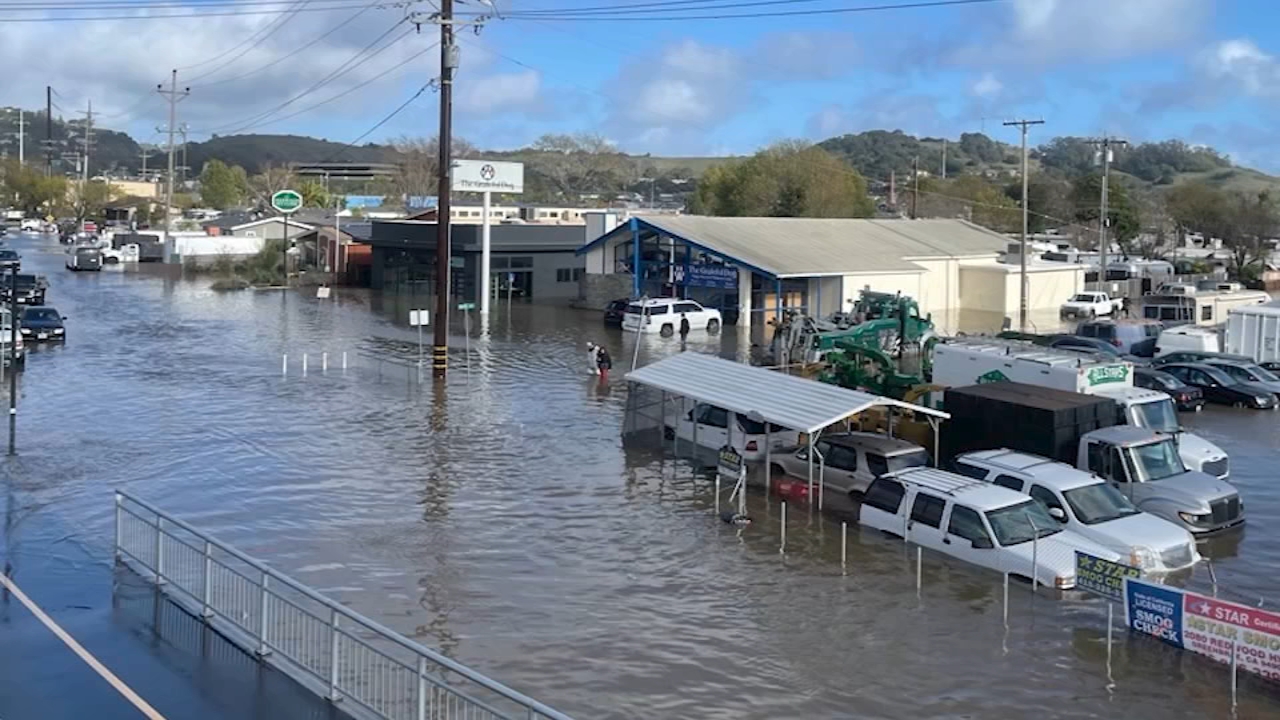
This past January, Carla and Ernie Cervantes' doggy daycare business in Marin turned into a swamp after the king tides swept through.
"It was flooding everywhere and the freeways were closed, we were OK... but then Saturday when the levee broke... everything was flooded. I mean it was like three or four feet of water," Carla Cervantes said.
The couple owns "The Grateful Dog," which has two locations in Greenbrae and San Francisco -- both in flood zones. And the Greenbrae facility got hit the hardest.
The parking lot... the backyard... even the freeway... all under water.
"Oh my frickin' God!" said Carla. "It was a Saturday when we actually had to evacuate dogs...so we evacuated everyone."
Federal law requires the Cervanteses to have flood insurance because the Marin facility is located in a flood zone.
"Thank goodness we did have the flood insurance because we had over $200K worth of damage to our facility," Carla said.
The catch?
"We have a $50K deductible," she said.
MORE: El Niño strengthens to highest category with 70% chance of record-breaking winter, new report says
According to the California Earthquake Authority, flood-related property damage in California is estimated to be $8 billion per year -- but FEMA reports less than 2% of the state actually has government flood insurance.
Amy Bach is the executive director and co-founder of United Policyholders.
Stephanie Sierra: "What is the biggest misconception people have about flood insurance?"
Amy Bach, United Policyholders: "That you don't need it -- if you don't live on the water."
Bach also explains you can get flood insurance from FEMA or through private insurers, but costs are much higher and often cover less.
"We know very few people carry flood insurance. So, the first message to your viewers, Stephanie, is... it's not covered by your home insurance policy," Bach continued. "You have to pay extra for it... in what's called an endorsement -- or buy a separate flood insurance policy."
"Where it rains it can flood... that's more true than it used to be," she said.
And now -- there's heightened demand for both options.
"Climate change has brought what are called severe convective storms... and basically there's a lot of rain falling in a short period of time. And it can overwhelm drainage systems and it can cause homes to flood where you wouldn't think that they would," she said.
Like her home, for example... in an area of San Francisco designated as "low vulnerability" to flooding. But she says during the last El Niño...
"We got heavy rain... it flowed right down... went all the way into our garage," Bach said.
Her garage drain was too clogged with leaves... leaving her with an expensive mess.
According to FEMA, more than 40% of flood claims occur outside designated high-risk flood zones.
So, even if you don't live in a high-risk area -- should you get insured?
"I would recommend that both homeowners and renters get flood insurance -- it may cost a certain amount of money but it's well worth it when it comes to repairing or rebuilding your home or replacing your possessions," said Michael DeLong, research and advocacy associate for the Consumer Federation of America.
40% of California flood insurance policyholders paid less than $1,000 for their policy, and 32% paid between $1,000 and $2,000 in 2023, according to data from the National Flood Insurance Program.
"The average national flood insurance policy provides coverage of up to $250K for your home and up to $100K for damage to your personal belongings... so just be aware if your home is more expensive than that...you may have to buy an additional flood insurance policy on top of that," Bach said.
As for whether it's worth it, Bach explains it's all about assessing your own risk.
"Is there a slope that leads toward your house? Has there been problems in the past with water pooling up? Are there large trees around your house... that in a storm could fall down or break a window?" she said.
And as you're answering those questions... remember what qualifies as "flooding" to insurance companies.
"(If) rain water (can) flow down toward your house... or easily rise up and get into your house, (you) should get a quote and if you can afford it -- buy flood insurance," Bach said.
And as you're answering those questions... remember this.
"Even flood insurance has an exclusion for earth movement. So it's a situation where the insurance company wants to come in and argue that it was earth movement that caused the flooding. That could still be a fight," said Bach.
Experts say the FEMA flood maps are typically out of date, relying heavily on historical information from the past. So, they may not reflect more recent events that can increase your risk, such as stormwater flooding caused by intense rain, sea-level rise and effects from climate change.
To help the Cervanteses and the Grateful Dog, visit their GoFundMe.
Take a look at more stories and videos by 7 On Your Side.
7OYS's consumer hotline is a free consumer mediation service for those in the San Francisco Bay Area. We assist individuals with consumer-related issues; we cannot assist on cases between businesses, or cases involving family law, criminal matters, landlord/tenant disputes, labor issues, or medical issues. Please review our FAQ here. As a part of our process in assisting you, it is necessary that we contact the company / agency you are writing about. If you do not wish us to contact them, please let us know right away, as it will affect our ability to work on your case. If we are able to assist, we will reach back out to you.